
 Windows & doors
 Kitchen remodeling
 Bathroom remodeling
 Home additions & ADU
 Roofing
 Driveway & pavers
 Fence
Free written scope consultation - allowances, timeline, and change-order rules on paper before a single trade is scheduled
Styles & brands we work with
- Kitchen remodeling
- Bathroom remodeling
- Home additions & ADU
- Roofing
- Windows & doors
- Driveway & pavers
- Fence
See the difference
 Before
 After
 Before
 After
 Before
 After
Do impact windows lower insurance in Irvine, CA? Yes, but not the way most homeowners expect
Impact windows can lower your insurance, but in Irvine the bigger effect is usually keeping your policy in force at all. Several major carriers have stopped writing or renewing policies in California’s wildland-urban interface (WUI) zones, and homes along Irvine’s eastern and southern edges sit squarely in that conversation. A documented fire-hardening package, impact-rated glazing included, gives an underwriter a reason to renew. For an exact read on your situation, call (888) 578-4462 and we’ll walk you through what we can put on paper for your carrier.
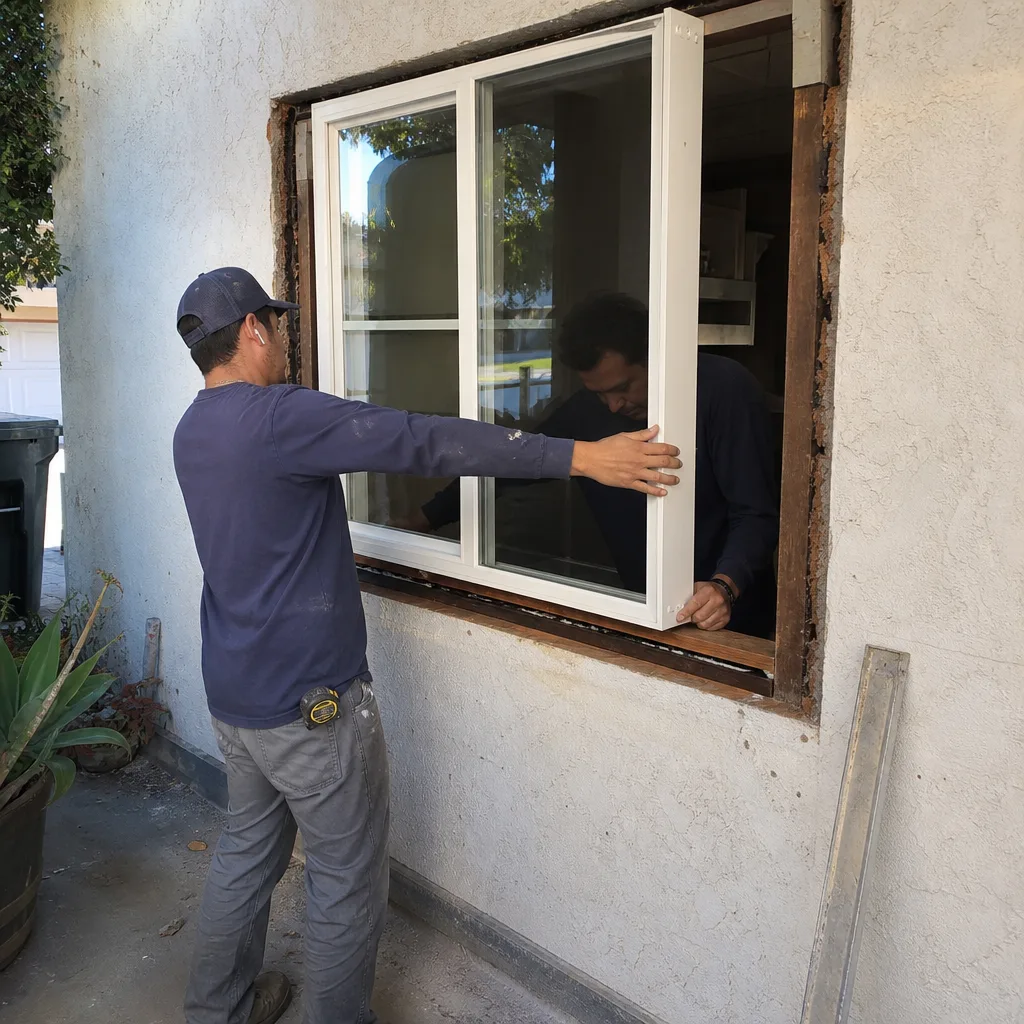
Irvine is a master-planned city built almost entirely over the last six decades, so most work happens inside village HOAs and design-review boards rather than across a patchwork of small jurisdictions. That matters here: your window swap may need both village architectural approval and the city building division’s sign-off, and an underwriter who sees permits and inspections behind the work reads that story very differently than one looking at an unpermitted install.
What California carriers actually ask about in Irvine’s WUI zones
Insurance companies don’t hand out discounts on a handshake. They work from checklists that look at roof class, vent screens, siding combustibility, and how the home performs under ember attack during Santa Ana wind events. Irvine’s dry summers and the defensible-space detailing required at the foothill edges make those details central rather than cosmetic.
Here’s the honest math: a 10-15% premium credit is real money, but it’s worth far less than a non-renewal notice. When a preferred carrier walks away, homeowners land on the California FAIR Plan, the insurer of last resort, which typically costs more for narrower coverage. If you’ve gotten that letter, the priority isn’t shopping a discount. It’s building a documented record of upgrades that shows the home is being actively hardened.
A few things we see on Irvine properties that trip up the checklist:
- Mismatched upgrades. A Class A tile roof with standard vents and combustible trim still fails most carrier fire-hardening checklists. The package has to be coherent.
- Impact glass sold as a fire upgrade. Impact rating and fire rating aren’t the same thing. Tempered, dual-pane impact windows from manufacturers like ES Windows and ECO Window Systems do real work against both wind-borne debris and radiant heat, but an underwriter wants to see them alongside door, vent, and roof hardening, not in place of it.
- Paperwork gaps. We’ve seen homeowners who did the right work and still got questioned because there was no permit record, no inspection sign-off, and no manufacturer spec sheet in hand.
What to look for in a fire-hardening window package
If you’re comparing bids, ask each contractor three questions: what impact rating the glass carries and from which manufacturer, whether they’ll pull permits and schedule inspections (not just hand you a receipt), and what in writing guarantees the install itself. On that last point, every project we run is covered by our 730-Day Done Right Promise, which also functions as a quality signal you can reference in an insurance conversation. It isn’t an insurance document, but a written workmanship guarantee behind the work says something to an underwriter that a handshake doesn’t.
For Irvine homes, we usually pair impact glazing with door and vent upgrades, and sometimes Class A roofing, into one project. That’s the advantage of working with a full-scope construction partner rather than a window-only outfit: your window, door, vent, and roof work can be sequenced as a single documented improvement instead of four separate jobs nobody can connect later. See what that looks like under Windows & Doors.
What does it cost? Impact window installation in Irvine runs roughly $8,000-$25,000 depending on the number of openings, framing changes, and how much HOA-approved architectural work is required. If your project involves noncombustible entry doors, a Therma-Tru option can run alongside the windows. Here’s a rough line-item view:
| Upgrade | Typical Irvine Range |
|---|---|
| Impact window installation (full home) | $8,000-$25,000 |
| Standard window replacement | $4,500-$15,000 |
| Roof replacement (Class A tile or composition) | $8,000-$20,000 |
| Metal roof installation | $15,000-$40,000 |
| Tile roof repair | $600-$2,500 |
Pricing is upfront and shown before work begins, so the number you see is the number you pay. If the full package is a stretch, 0% financing for 18 months and $1,000 off projects over $10,000 take some of the sting out of doing it right the first time. We’re licensed and insured, and our technicians bring up to 12 years of experience to each job.
Does documentation really matter to an underwriter?
Yes, and it’s the part most homeowners underestimate. A building permit, inspection sign-off, and manufacturer spec sheet together tell a carrier exactly what was installed and to what standard. An unpermitted install doesn’t. We pull permits and schedule inspections as part of the process, which means you walk away with a paper trail you can submit directly to your carrier as evidence of upgrade.
Can impact windows alone keep my policy?
Rarely. Most California carrier fire-hardening checklists want the whole envelope addressed, which is why we look at windows, doors, vents, and roofing together before recommending a scope. A single-trade install can still help, but a coherent package tells the story underwriters are looking for. If you’re not sure where your home stands, a no-pressure assessment on site is the fastest way to find out, and we’re happy to loop your insurance agent in on what we find. You can also see the full range of work we handle across our Irvine service area.
Calls are answered by a live person 24 hours a day, so you don’t have to wait until Monday for a straight answer.
FAQs
Sometimes, but the more common outcome is that a documented fire-hardening package helps keep your current carrier from non-renewing you, which is worth far more than a modest premium credit. Impact glazing combined with roof, vent, and door upgrades gives an underwriter a reason to stay. Call (888) 578-4462 for an exact read on your policy situation, free of charge.
Impact window installation in Irvine typically runs $8,000-$25,000, with the range driven by the number of openings, framing changes, and HOA architectural requirements. Standard replacement runs $4,500-$15,000. Call (888) 578-4462 for a free estimate and design consult on your specific home.
Usually not. Most carrier checklists want Class A roofing, ember-resistant vents, and noncombustible siding and doors alongside the glazing, so window-only work often falls short of the full standard. Combining them into one documented project tells a stronger story to an underwriter. Call (888) 578-4462 to plan the package.
Many homeowners end up on the California FAIR Plan as a fallback, which usually means higher cost for narrower coverage, so the better play is to give your carrier documented proof of hardening before renewal comes around. A permit-pulled, inspection-passed project is exactly that proof. Call (888) 578-4462 to get started.
If you’d rather have it looked at than guess, Groundwork Construction Co. of Irvine offers a no-pressure assessment in Irvine. Call (888) 578-4462 for a free estimate, and we’ll put together a scope you can hand straight to your carrier.
Written by the team at Groundwork Construction Co. of Irvine, serving Irvine, CA.